Does Norway charge VAT or duty on an original painting imported from Brazil?
Norway's main rule is that VAT is payable on art you import, at 25% for most goods. Customs says a resident who buys directly from the living artist abroad or via an artist's intermediary should not pay it. If it counts as art but arrives another way, the base is 20% of its value. Duty is a separate line.
What is the general rule for art entering Norway?
Norwegian Customs (Tolletaten) states the main rule plainly: you pay value added tax on artworks you import into Norway, and in certain cases full or partial exemption can be approved. Its general calculation page gives the VAT rate as 25 percent for most goods, and says the basis is the goods' customs value plus any duty, excise or fees. That customs value is what was paid or is payable abroad, including transport to Norway, insurance and packing costs, converted to Norwegian kroner at weekly rates set by Customs.
Duty is a separate line. Tolletaten's import guide says most goods carry no customs duty, and that in simplified terms duty applies to textiles such as clothing and to foodstuffs. It adds that any duty rate is tied to the goods' number in the customs tariff. This page did not read the tariff entry for paintings, so it states no duty figure for them. The tariff is the place to confirm it on the day of shipment.
When can a painting from a living artist be VAT-exempt?
Tolletaten sets two conditions for full exemption: the work must count as an artwork under the VAT regulation (merverdiavgiftsforskriften, section 1-3-2), and it must be made by a living artist who imports it personally. The page extends this. A person resident in Norway who buys an artwork directly from the artist abroad, or through an intermediary such as a gallery representing the artist, should not pay VAT either. In the words of the page, the exemption applies regardless of who is named as recipient on the declaration, as long as the import comes directly from the artist or from the artist's intermediary.
The same page draws a line on the other side. If the work is bought from someone other than the artist, for example a gallery that does not represent the artist, Customs does not grant the exemption, and a gallery is not treated as the artist's intermediary in that situation. Works by deceased artists are not covered either.
What if the exemption does not apply?
Tolletaten describes two further outcomes. If the work is not imported by the artist or the artist's intermediary but still counts as art under section 1-3-2, the calculation base is set to 20% of the work's value, including freight and insurance. The Tax Administration's guidance cites the Norwegian VAT Act, section 4-11, for the same 20% base. If the work does not count as art under that section, VAT is payable on the whole value, including freight and insurance, for living and deceased artists alike.
An illustration of the arithmetic, not a quote or a forecast: taking the general 25% rate for most goods and the 20% art base, which no source read here combines for art, a total value of 1,000 (freight and insurance included) would give a base of 200, and 25% of 200 is 50. Your own figure depends on the rate that applies to the work, the declared value, the weekly exchange rate and how the work is classified.
Who declares the painting, and where is the exemption claimed?
Tolletaten's import guide says everyone bringing goods into Norway must report them to Customs, including private imports, and that the declaring party is responsible for paying or reporting duty and other charges. A customs representative can usually declare on the importer's behalf, though the importer remains responsible for the import being done in line with the rules. Private individuals are exempt from the requirement to declare electronically; they fill in an import declaration and present documents such as the invoice and freight papers at a customs office. For online purchases, Customs adds that a carrier declaring on your behalf needs your 11-digit national identity number.
On the exemption itself, the Tax Administration's guidance says VAT-unregistered importers claim it themselves in box 44 of the customs declaration, using code M2, and Tolletaten's art page says it is up to the importer to document that the conditions are met. Private buyers pay import VAT to Customs; VAT-registered businesses report it to the Tax Administration instead. For the studio's terms: freight and any duties or taxes in the destination country are paid by the buyer.
From the studio
From the studio
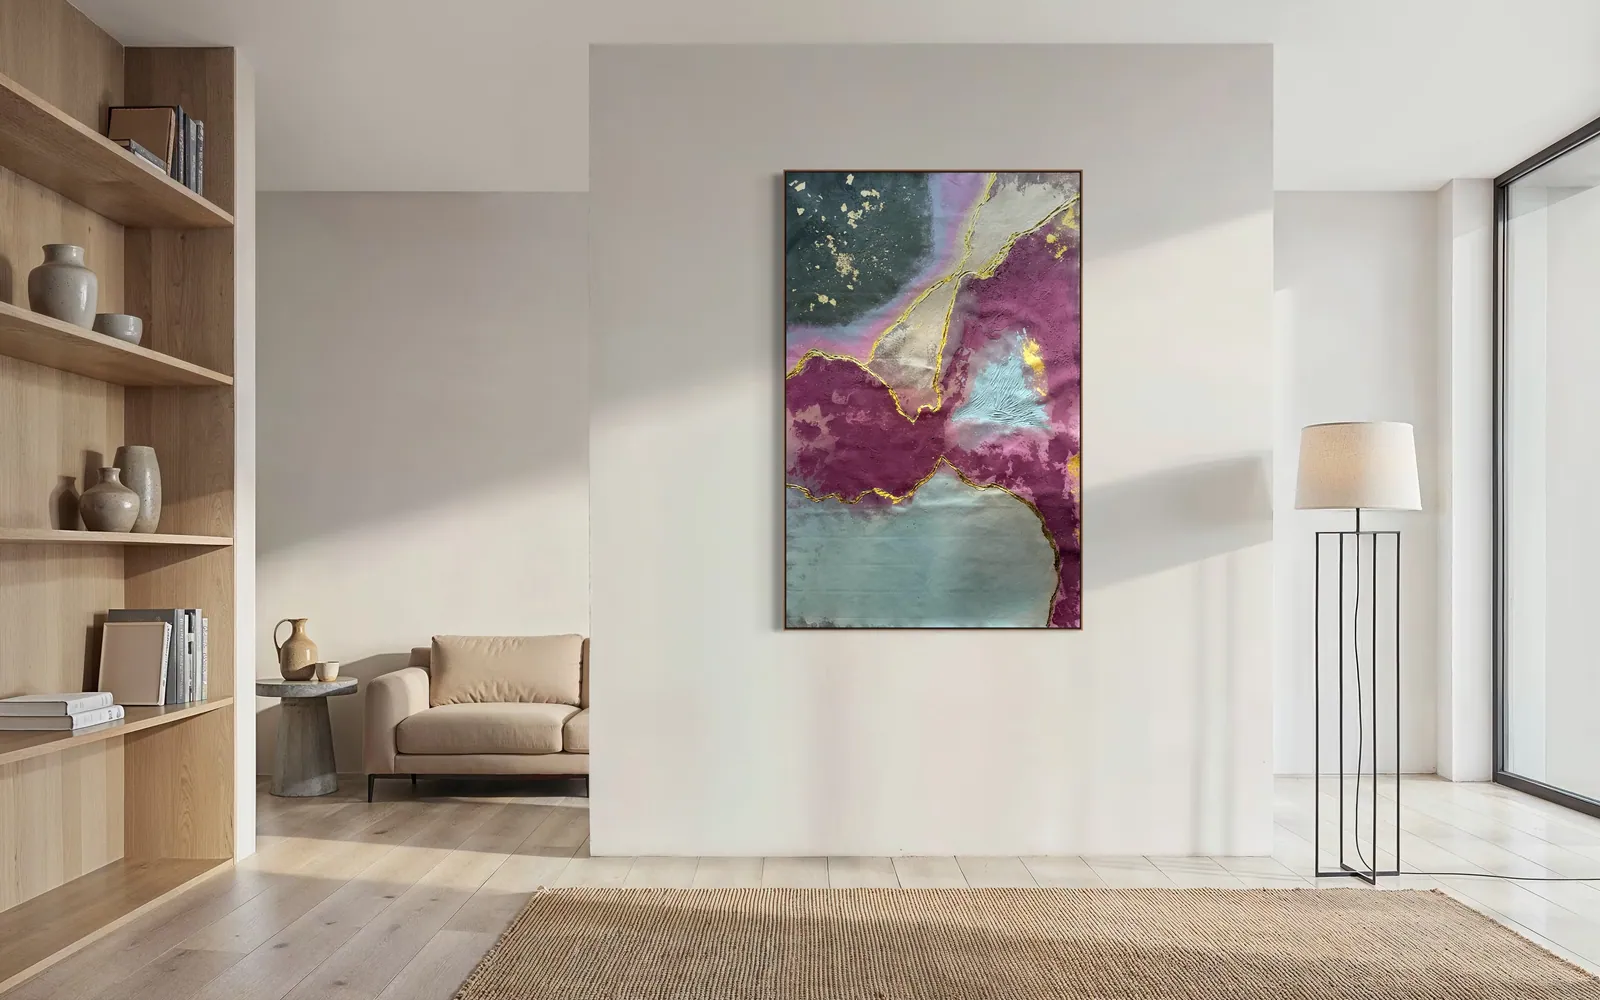
What strikes me in the Norwegian text is how much turns on two plain facts: who made the work, and who it is bought from. Both are the kind of detail I keep on record for every painting. Take Quartz Seam, in the Terra & Ether series: 98 x 152 cm, mixed media with acrylic and imitation gold leaf on canvas, painted in 2026 (Archive ID AP-TAE-2026-007). The signed certificate carries the full technical record of the work and that Archive ID, and the acquisition is direct from me, with a fiscal invoice or official receipt. Whether those papers satisfy Norwegian Customs is for the declaration to decide, not for me.
This text is informational and is not tax or customs advice; confirm with the customs authority or a broker.
Frequently asked
Does Norway charge VAT on an original painting imported from Brazil?
As a main rule, yes: Tolletaten says VAT is payable on artworks imported into Norway, at 25 percent for most goods. There is an exemption for a living artist's own original work, which also covers a Norway-resident buyer purchasing directly from the artist abroad or through the artist's intermediary. If the exemption does not apply but the work counts as art, the base is 20% of its value including freight and insurance. Whether a given work qualifies is decided in the declaration.
Is an original painting treated differently from a print when it enters Norway?
The sources read for this page do not say how a print is treated. Norwegian Customs ties the exemption and the 20% base to whether the item counts as an artwork under the VAT regulation, section 1-3-2. If the item does not count as art under that section, VAT applies to the whole value including freight and insurance. This page did not read the full text of that definition, so it does not say which items it covers. Check the regulation, or ask Customs or a broker, before relying on any one description.
Who declares the painting to Tolletaten customs: the buyer, the seller or the carrier?
Tolletaten's import guide says the importer is responsible for payment or reporting and for the declaration being done in line with the rules. A customs representative, often the carrier's, can usually declare on the importer's behalf, and a private person can instead declare at a customs office. For online purchases, Customs says a carrier declaring for you needs your 11-digit national identity number. The seller is not named as the declarant in the sources read.
What documents usually accompany a painting entering Norway?
Tolletaten says a private person declaring at a customs office brings documentation such as the invoice and freight papers. For the artist exemption, its art page says it is up to the importer to document that the conditions are met, meaning that the work is by a living artist and was bought directly from the artist or the artist's intermediary. Perfeito Studio's acquisitions include a fiscal invoice or official receipt and a signed Certificate of Authenticity.
Do I need a customs broker to receive a painting in Norway?
The guides read do not require one for a private person: Tolletaten says private individuals can declare at a customs office, and that a customs representative can usually declare for you. In practice a carrier often acts as that representative, and Customs notes carriers charge a declaration fee. Even with a representative, the importer stays responsible for the declaration, so confirm who files it and with what data before the work ships.
Considering a painting for a home in Norway?
Tell us the work and your city. We will confirm the documents that come with the painting and quote shipping before you decide.
Sources
- Tolletaten (Norwegian Customs), 'Kunstverk og meirverdiavgift' — 2026-10-08
- Tolletaten (Norwegian Customs), 'Beregning av tollavgift og andre avgifter' — 2026-10-08
- Tolletaten (Norwegian Customs), 'Importguide' — 2026-10-08
- Tolletaten (Norwegian Customs), 'Handle frå ein nettbutikk som ikkje er VOEC-registrert' — 2026-10-08
- Skatteetaten (Norwegian Tax Administration), 'Faglige avklaringer mv. knyttet til innførselsmerverdiavgiften' — 2026-10-08
Published on · Updated on